Published - 14 Hours Ago
Financial Planning for Doctors: Clinic Management and Growth
Financial Planning for Doctors: How to Manage Clinic Finances and Build a Sustainable Medical Practice
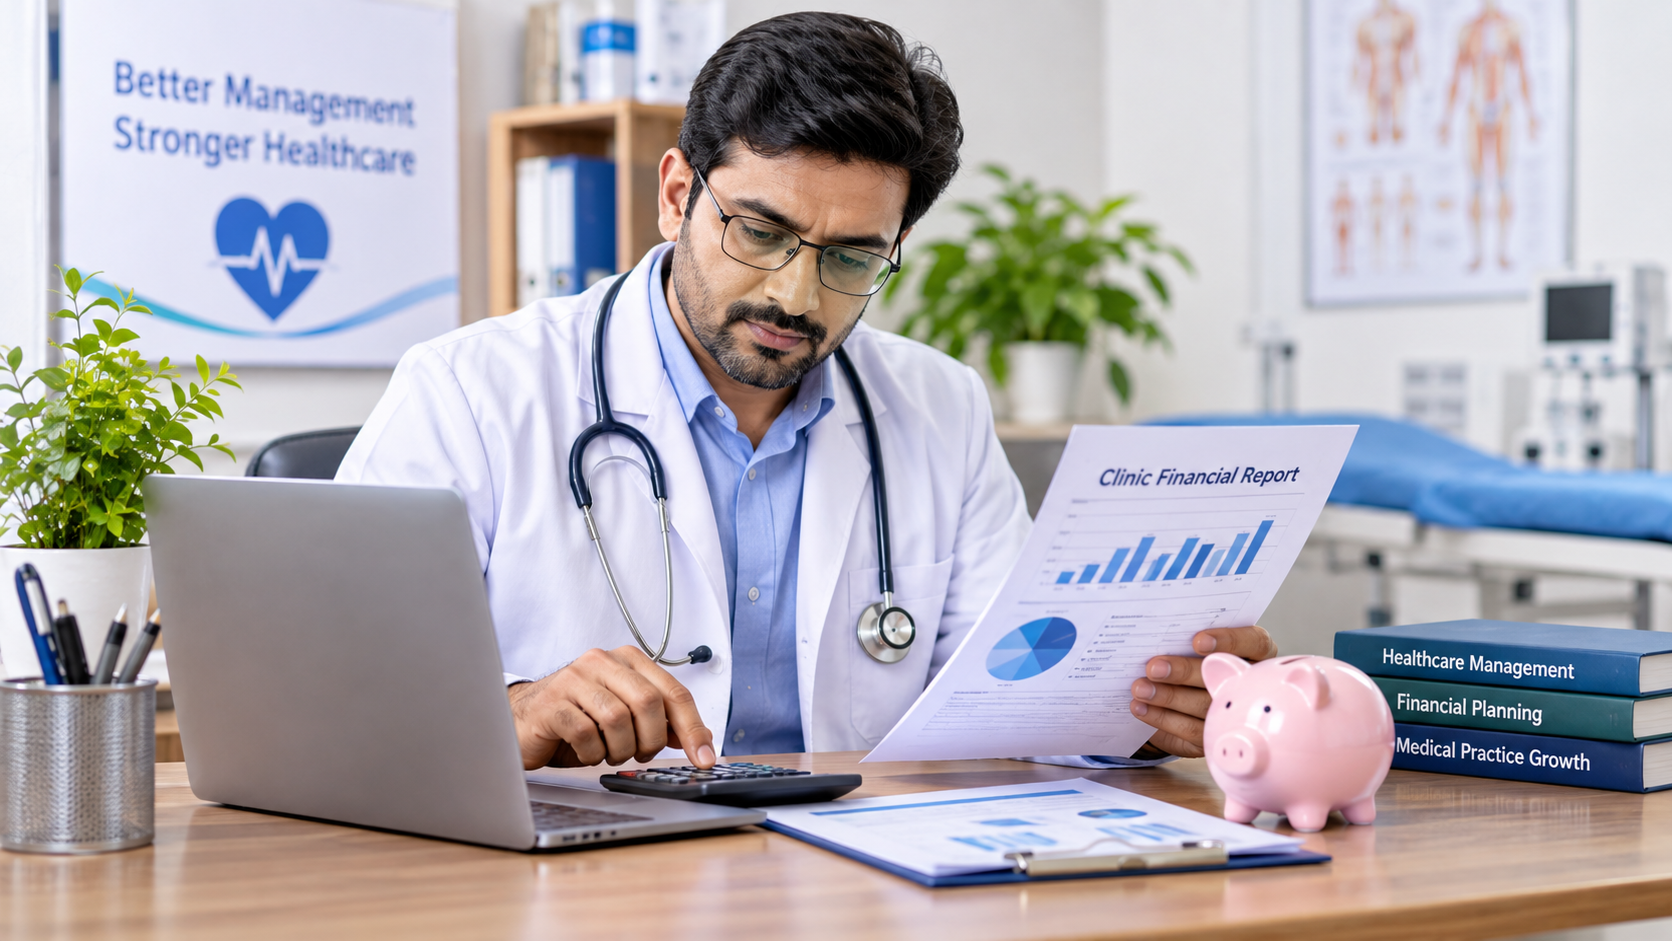
Running a successful medical practice requires more than clinical expertise and the ability to provide quality patient care. Doctors who establish their own clinics must also understand financial planning, expense management, revenue generation, and daily business operations.
Many healthcare professionals focus primarily on treating patients but underestimate the financial and administrative responsibilities involved in managing a medical practice. Expenses such as rent, staff salaries, medical equipment, electricity, maintenance, and medical supplies can quickly add up. Without proper financial planning, even a clinic with a steady flow of patients may experience financial difficulties.
Financial planning plays an important role in ensuring that a medical practice remains financially stable while continuing to deliver quality healthcare services.
From preparing a realistic budget to managing cash flow and investing in technology, doctors need to develop essential financial management skills to build a sustainable practice.
In this article, we explore the key aspects of financial planning and clinic management, practical strategies doctors can implement, and real-world healthcare case studies that demonstrate how better financial and operational management can improve clinic performance.
Why Financial Planning Is Important for Medical Practices
Financial planning helps doctors understand how much money their clinic earns, how much it spends, and where improvements can be made.
A clinic may receive a considerable number of patients every day, but high patient volume does not automatically translate into financial stability. Poor expense management, delayed payments, inefficient billing, and unnecessary purchases can reduce profitability.
Effective financial planning helps doctors:
Understand their clinic's financial position.
Prepare monthly and annual operating budgets.
Control unnecessary expenses.
Maintain sufficient cash flow.
Plan investments in medical equipment and technology.
Manage staff salaries and operational costs.
Prepare for unexpected financial challenges.
Identify opportunities for sustainable growth.
Financial planning should not be treated as a one-time activity. Doctors should regularly review their clinic's financial performance and adjust their plans according to changing operational requirements.
1. Understanding the Financial Needs of a Medical Practice
Before establishing a clinic or expanding an existing one, doctors should understand the financial requirements involved in running the practice.
These expenses can generally be divided into three categories.
Initial Setup Costs
These are expenses incurred when establishing a new clinic.
Common examples include:
Renting or purchasing clinic space.
Interior design and renovation.
Medical equipment and diagnostic instruments.
Furniture and waiting-room arrangements.
Computers and practice management software.
Licences, registrations, and professional services.
The initial investment depends on the clinic's specialty, location, size, and services offered.
Fixed Operating Costs
Fixed costs are recurring expenses that generally remain stable over a particular period.
Examples include:
Monthly rent.
Staff salaries.
Internet and software subscriptions.
Insurance premiums.
Equipment financing payments.
Certain maintenance contracts.
Understanding fixed expenses helps doctors calculate the minimum monthly revenue required to keep the clinic operational.
Variable Operating Costs
Variable expenses change depending on patient volume and clinical activities.
These may include:
Medical consumables.
Diagnostic supplies.
Laboratory materials.
Utility consumption.
Cleaning supplies.
Equipment servicing and repairs.
Separating expenses into these categories makes budgeting easier and helps doctors identify areas where cost management may be improved.
2. Budgeting and Managing Clinic Expenses
A well-prepared budget provides a financial roadmap for a medical practice.
Doctors should prepare a monthly operating budget that includes expected revenue, fixed expenses, variable expenses, and planned investments.
For example, a small outpatient clinic may prepare a monthly budget covering rent, salaries, electricity, medical supplies, software, equipment maintenance, and other administrative costs.
The actual figures will depend on the clinic's location, specialty, and size.
Practical strategies for better expense management
Track Every Expense: Maintain accurate records of purchases, payments, salaries, and other operational expenses.
Review Supplier Agreements: Compare suppliers periodically and evaluate whether existing agreements provide appropriate value and quality.
Monitor Inventory: Maintain an organised inventory system to avoid excessive purchasing, expired products, and unnecessary stock accumulation.
Avoid Unnecessary Investments: Purchase equipment according to actual clinical requirements rather than investing in expensive technology that may remain underutilised.
Review Monthly Performance: Compare actual expenses with the planned budget to identify unexpected increases.
Expense management should never compromise patient safety, clinical quality, or the standards required for medical equipment and supplies.
3. Setting Consultation Fees and Pricing Medical Services
Consultation fees are an important component of a clinic's financial planning.
Doctors should establish their pricing structure by considering the costs involved in providing services, their specialty, local market conditions, patient requirements, and applicable professional and regulatory considerations.
A pricing decision should account for:
Clinic rent and operational expenses.
Staff and administrative costs.
Medical equipment and maintenance.
Time spent with each patient.
The complexity of services provided.
Local healthcare affordability.
For example, a specialist clinic providing longer consultations or additional diagnostic services may have a different cost structure from a general outpatient practice.
Doctors should regularly review their pricing structure to ensure that it remains financially sustainable and transparent to patients.
It is equally important to communicate consultation charges and service costs clearly before providing services.
4. Managing Cash Flow and Clinic Revenue
Cash flow is one of the most important aspects of clinic management.
It refers to the movement of money into and out of a medical practice.
A clinic may generate revenue through consultations, diagnostic services, procedures, health packages, and other legitimate medical services. However, delayed payments and poor financial tracking can create cash flow problems.
For example, a clinic that provides services through insurance or third-party administrators may have to wait for reimbursement after submitting claims.
During this period, the clinic still needs to pay salaries, rent, suppliers, and other operational expenses.
Ways to improve cash flow
Maintain accurate billing records.
Collect payments promptly according to the clinic's payment policy.
Submit insurance claims with complete and accurate documentation.
Monitor pending payments regularly.
Follow up on rejected or delayed claims.
Maintain a monthly cash flow statement.
Keep an appropriate financial reserve for unexpected expenses.
Doctors should also distinguish between revenue generated, payments received, outstanding receivables, and actual operating profit.
These figures provide different information about the financial health of a practice.
5. Investing in Medical Equipment and Technology
Medical equipment and digital technology are essential investments for modern healthcare practices.
However, every investment should be evaluated according to its clinical value and financial impact.
Before purchasing new equipment, doctors should consider:
Initial purchase cost.
Installation and maintenance expenses.
Staff training requirements.
Expected patient demand.
Equipment lifespan.
Potential revenue contribution.
Clinical benefits and patient safety.
Technology can also improve the administrative side of clinic management.
For example, practice management systems can help organise appointments, maintain billing records, manage patient information, and monitor daily operations.
Electronic health records can reduce dependence on paper-based documentation and make relevant patient information easier to access.
The objective should not simply be to purchase more technology. It should be to identify solutions that improve efficiency, support better patient care, and provide long-term value.
6. Managing Staff Salaries and Operational Costs
Staff members play an important role in the daily functioning of a medical practice.
Receptionists, nurses, administrative employees, technicians, and other healthcare professionals contribute to patient experience and clinic efficiency.
However, staff salaries also represent a significant recurring expense.
Doctors should plan staffing requirements according to patient volume, clinical services, operating hours, and administrative responsibilities.
Important staff management considerations
Define Roles and Responsibilities: Every employee should understand their responsibilities and reporting structure.
Plan Staff Schedules: Organise shifts according to patient appointments and operational requirements.
Invest in Training: Staff training can improve communication, documentation, billing accuracy, and patient coordination.
Monitor Workload: Ensure that responsibilities are distributed appropriately to avoid unnecessary administrative pressure.
Review Staffing Costs: Regularly evaluate whether staffing arrangements meet the clinic's operational needs without compromising service quality.
Effective staff management improves both operational efficiency and the overall patient experience.
7. Using Financial Reports to Make Better Decisions
Doctors should not depend only on their bank balance to evaluate the performance of their clinic.
Financial reports provide a clearer understanding of how the practice is performing.
Some important reports include:
Profit and Loss Statement
This report summarises the clinic's income and expenses over a specific period. It helps doctors understand whether the practice is generating an operating profit or experiencing a loss.
Cash Flow Statement
This report tracks the money entering and leaving the business. It helps identify potential liquidity problems.
Balance Sheet
A balance sheet provides information about the clinic's assets, liabilities, and owner's equity at a particular point in time.
Accounts Receivable Report
This report tracks outstanding payments from patients, insurance providers, or other parties.
Monthly Expense Report
This report helps doctors identify where money is being spent and compare actual costs with the planned budget.
Reviewing these reports regularly allows doctors to identify financial problems early and make better-informed decisions.
8. Real-World Case Studies: How Better Financial Management Improves Healthcare Operations
Understanding financial management becomes easier when we examine real healthcare organisations that have improved their financial and operational performance through better systems and processes.
The following examples demonstrate how effective revenue management, billing improvements, and operational planning can contribute to better financial outcomes.
Case Study 1: Brownsville Community Health Centre – Improving Revenue Collection
One useful example comes from the Brownsville Center, documented by The Commonwealth Fund.
The organisation faced challenges in generating sufficient revenue to sustain its healthcare services. It participated in a Revenue Maximization (RevMax) Learning Collaborative to improve its collection processes and financial management.
The programme focused on improving billing practices, reducing delays between service delivery and billing, addressing rejected claims, and strengthening internal financial controls.
Reported results included:
Average weekly cash receipts increased by 46%.
Reimbursement per visit increased by 55%, from $78 to $121.
Total revenue increased by 51%, representing an additional $345,000.
Patient visit volume increased by 5%.
This case demonstrates the importance of managing the complete revenue cycle rather than focusing only on attracting more patients.
For independent medical practices, the key lesson is to maintain accurate billing records, collect payments efficiently, monitor rejected claims, and establish clear financial responsibilities.
Source: The Commonwealth Fund – Revenue Maximization Program at the Brownsville Center
Case Study 2: Clinics of North Texas – Improving Revenue Cycle Management
Clinics of North Texas provides another example of how better revenue cycle management can improve financial performance.
The practice worked with an external revenue cycle management team to improve billing operations, address denied claims, monitor payments, and identify documentation issues.
The organisation also received support in tracking payer policy changes and improving its revenue collection processes.
Reported results included:
Annual revenue increased by 20% after the transition.
Average days in accounts receivable decreased from 36 to 23.
The proportion of accounts receivable under 90 days increased from 16% to 56%.
Gross collection rate improved by 1.64 percentage points.
The case highlights how accurate documentation, regular claim follow-up, and organised billing systems can reduce administrative inefficiencies.
For doctors managing independent clinics, an important takeaway is that every consultation and service should be documented and billed accurately.
Source: Medical Group Management Association (MGMA) – Using an RCM Solution to Maximize Revenue and Reduce Administrative Burden
Case Study 3: A Medical Group's Operational Transformation – Reducing Costs and Improving Efficiency
A case study published by Baker Tilly describes how a medical group improved its operations by introducing lean management principles.
The organisation focused on improving appointment scheduling, organising clinical workspaces, managing inventory, and strengthening revenue cycle processes.
These changes helped reduce operational inefficiencies and improve the use of available resources.
Reported results included:
More than 10,000 additional annual appointment opportunities.
Approximately $155,000 saved through reduced appointment no-shows.
More than 900 square feet of workspace reclaimed.
Over 4,400 annual staff hours freed through revenue cycle improvements.
An estimated $1.7 million in financial improvement since 2017.
Although this example involves a larger medical group rather than a small independent clinic, its principles can be applied to practices of different sizes.
Doctors can begin with simple improvements such as better appointment scheduling, inventory tracking, clearly assigned staff responsibilities, and organised billing workflows.
Source: Baker Tilly – Case Study: Health System Becomes a Lean Enterprise
What Can Independent Doctors Learn from These Case Studies?
These examples highlight several practical lessons:
Increasing patient numbers is not the only way to improve financial performance. Better billing and collection processes also matter.
Accurate documentation helps reduce billing errors and payment delays.
Appointment scheduling and reminder systems can reduce avoidable operational losses.
Inventory management can prevent unnecessary expenditure.
Regular financial reporting helps identify problems before they become serious.
Efficient administrative processes allow doctors and staff to spend more time on patient care.
The results reported in these case studies relate to specific organisations and should not be treated as guaranteed outcomes for every clinic.
9. Common Financial Mistakes Doctors Should Avoid
Even experienced healthcare professionals can encounter financial difficulties when managing their own practices.
Some common mistakes include:
Mixing Personal and Business Finances
Doctors should maintain separate records and accounts for personal and clinic-related transactions. This makes financial tracking and accounting more organised.
Not Preparing an Operating Budget
Without a budget, it becomes difficult to identify unnecessary expenses or plan future investments.
Ignoring Outstanding Payments
Unpaid invoices and delayed reimbursements can create cash flow problems. Regular monitoring of outstanding payments is essential.
Overinvesting in Equipment
Purchasing expensive equipment without evaluating patient demand, maintenance requirements, and expected utilisation can create unnecessary financial pressure.
Ignoring Financial Reports
A clinic may appear busy while experiencing poor financial performance. Regularly reviewing financial statements helps doctors understand the actual position of their practice.
Not Planning for Unexpected Expenses
Equipment breakdowns, emergency repairs, and temporary reductions in patient volume can affect clinic finances. Maintaining an appropriate financial reserve can help manage unexpected situations.
10. Strategies for Long-Term Clinic Growth
Financial stability is not only about reducing expenses. It also involves creating a sustainable operational model that supports future growth.
Doctors can consider the following strategies:
1. Develop a Long-Term Financial Plan
Prepare financial projections for the next 12 months and review them periodically. Include expected revenue, operational expenses, planned investments, and potential risks.
2. Improve Patient Experience
Clear communication, organised appointments, professional staff, and efficient clinic operations can support patient satisfaction and long-term trust.
3. Use Digital Practice Management Tools
Digital systems can improve appointment scheduling, documentation, billing, and reporting.
4. Monitor Clinic Performance Indicators
Track important indicators such as monthly revenue, operating expenses, patient no-show rates, outstanding payments, and appointment utilisation.
5. Evaluate Expansion Carefully
Before opening another branch or introducing a new service, evaluate the financial requirements, patient demand, staffing needs, and operational risks.
6. Work With Financial Professionals
Chartered accountants and qualified financial advisors can help doctors with accounting, taxation, compliance, financial forecasting, and investment planning.
A combination of clinical expertise, financial awareness, and effective management can help build a sustainable medical practice.
Conclusion
Financial planning is an essential part of managing a successful medical practice. Doctors need to understand not only how to provide quality healthcare but also how to manage the financial and operational responsibilities involved in running a clinic.
From preparing budgets and controlling expenses to managing cash flow, investing in technology, and analysing financial reports, every aspect of financial management contributes to the long-term stability of a practice.
The real-world case studies discussed in this article demonstrate that improvements in billing, revenue collection, scheduling, and operational efficiency can create meaningful financial benefits for healthcare organisations.
However, every clinic has different requirements depending on its specialty, location, size, and patient population. Financial strategies should therefore be adapted to the specific needs of each practice.
As healthcare continues to evolve, doctors who develop both clinical and management skills will be better prepared to establish sustainable practices, improve operational efficiency, and deliver quality patient care.
Ultimately, successful clinic management is about maintaining the right balance between financial sustainability, operational efficiency, and patient-centred healthcare.
Created by

Rigomo Team
Rigomo is a leading online education platform that offers a wide range of courses to help individuals enhance their skills and achieve their career goals. With our user-friendly interface and expert instructors, we strive to provide high-quality education to everyone, anytime and anywhere. Join us today and take the first step towards a brighter future.
Rigomo is an e-learning platform that was founded in 2019 by a team of dedicated professionals with a passion for revolutionizing the way people learn. The platform offers a range of online courses that cover various industries, including business, technology, healthcare, and more.
Rigomo's courses are designed to be interactive and engaging, with a focus on practical skills that learners can apply in their careers. The platform uses a combination of video lectures, quizzes, and hands-on projects to help learners master the subject matter.
Rigomo is committed to providing affordable and accessible education to people around the world. The platform offers a range of pricing options, including monthly and annual subscriptions, as well as pay-as-you-go options for individual courses.
Since its launch, Rigomo has received numerous accolades for its innovative approach to e-learning. The platform has helped thousands of learners across the globe acquire new skills and advance their careers.
As Rigomo continues to grow, the team remains committed to providing high-quality education that is accessible to all. The platform is constantly updating its courses and features to ensure that learners have access to the latest tools and technologies.
Comments (0)
Search
Popular categories
Health and Wellness
233Skill Development
8Technology
5Community Impact
2Success story
2Creativity
1Latest blogs
Financial Planning for Doctors: Clinic Management and Growth
14 Hours Ago
Beyond Blood Sugar: How Continuous Glucose Monitoring Is Transforming Diabetes Management
2 Days Ago
Online Clinical Courses for Doctors to Build Practical Skills
Thu, 27 Aug 2026
Write a public review